How to Pay for Drug Rehab
Paying for rehab can involve insurance, public coverage, financial assistance, or self-pay arrangements. Written estimates and coverage checks help separate the advertised price from the costs you may actually owe.
Battling addiction & ready for help?
On this pageJump directly to a section.Show topicsHide topics
Finding a Way to Afford Rehab
If rehab seems unaffordable, there may be options beyond the first price you see, including insurance, public services, and financial assistance. Start with the care you need, then confirm what is covered and what you would owe. If you are uninsured, begin with available public or lower-cost services. Eligibility and availability vary, but you can ask for help finding a workable option.[1][2]
- Coverage is plan-specific. Confirm the service, provider, network, and authorization requirements.[1]
- A metal tier is not your rehab bill. Marketplace categories describe estimated cost sharing across covered care; actual costs vary by plan.[3]
- Ask what is billed separately. One facility quote may not include every clinician or service.[4]
- Uninsured or self-pay patients can request an estimate. CMS explains the requirements and the limits of good faith estimates.[4]
Why There Is No Single Rehab Price
Treatment can involve overnight care, structured daytime services, routine appointments, medication, or several phases of care. Those are different services with different billing arrangements. Start with a clinical assessment and ask what is recommended before comparing prices for programs that may not provide equivalent care.[5][6]
Ask whether a quote covers the full proposed service or only one part of it. Examples to clarify include the facility, professional visits, tests, medications, transportation, and continuing care. The question is what you may actually be charged, not only the advertised program price.
Check What the Rehab Quote Includes
“What does this estimate include, what is billed separately, and what could change the total?” Request the answer in writing so you can compare it with the insurer’s explanation and later bills.
Different rehab services may have separate bills. If you need medical detox, confirm what withdrawal care costs and which ongoing treatment is excluded from that quote. Ask the provider to identify each stage before you compare the total with another program.[7]
Using Health Insurance for Rehab
Call the number on the back of your insurance card with the provider’s name and recommended service ready. Ask whether your plan has a case manager who can help find care that meets your medical and financial needs. Also request participating providers nearby and coverage details for the proposed treatment. SAMHSA identifies these as useful questions for your insurer.[1]
Work through these questions with the insurer:
- Is this specific facility and provider in network?
- Is the recommended level of care covered?
- Do I need authorization or a referral before treatment?
- What deductible, copayment, or coinsurance applies?
- Are clinician visits, medicines, and tests billed under separate terms?
- Whom do I contact if a service or payment is denied?
Record the date, representative’s name or reference number, and the information given. Then ask the provider how its estimate reflects those terms. This is a practical way to keep the two conversations connected; a verbal estimate is not a guarantee of the final claim payment.
Coverage and Your Share of Costs
An insurance plan may cover a service while still requiring you to pay part of the cost. A deductible is an amount you pay before certain plan payments begin; copayments and coinsurance are other forms of cost sharing. Ask which terms apply to each part of your treatment.[1]
Do not assume an in-network facility means every separately billing clinician or service has the same status. Ask the facility to identify the organizations involved, then verify coverage with the insurer. “Insurance accepted” is the beginning of the coverage conversation, not the answer.[1]
Marketplace Plans and Mental Health Benefits
HealthCare.gov states that Marketplace plans cover mental health and substance use disorder services as essential health benefits. Specific benefits and out-of-pocket costs vary by state and plan. Coverage requirements do not mean every facility, service, or program length is paid in full.[8]
Marketplace coverage also includes protections related to pre-existing conditions and parity for mental health and substance use disorder benefits. For a coverage problem, ask the insurer to explain the decision and available review process. Use the plan’s documents and official help resources for the specific situation.[8]
What Bronze, Silver, Gold, and Platinum Mean
Marketplace metal categories describe how a plan and its members generally share costs for covered services. HealthCare.gov emphasizes that actual costs vary by plan and that a category does not describe quality of care. Do not multiply a rehab quote by a metal-tier percentage to predict your bill.[3]
For example, a category’s estimated share does not settle whether a particular program is in network, whether a service is covered, or how your deductible applies. Ask for the actual benefits and estimate. Those details are more useful than the color of the plan category.[3][1]
Medicare, Medicaid, and Other Public Coverage
Public coverage can be a route to treatment, but eligibility, participating providers, and covered services need to be checked for the particular program and person. SAMHSA’s payment resources can help you identify coverage and assistance options. Do not assume that a program accepts a benefit simply because another nearby program does.[2][1]
Ask a benefits representative or the relevant public program about enrollment and coverage. The facility should explain whether it participates and which services it can bill. If the first option does not accept your coverage, ask for help locating one that does.
Medicare Outpatient Program Benefits
Medicare has separate coverage information for intensive outpatient and partial hospitalization services. Its IOP benefit includes a care-plan requirement for at least nine hours of therapeutic services weekly; its PHP description includes at least 20 hours and certification that inpatient treatment would otherwise be needed. Other requirements also apply.[9][10]
These benefit rules do not mean every service advertised as IOP or PHP is covered. Confirm the provider, setting, service eligibility, and your share of costs. Medicare does not cover meals or transportation to and from treatment under its PHP mental health benefit; include those expenses in your planning.[10]
If You Do Not Have Insurance
Start with a service that can help you find affordable care. Your state or county health services department can point you toward local health resources, and SAMHSA lists free or low-cost treatment options. When contacting a provider, say that you are uninsured and ask about reduced fees, public funding, or assistance before discussing a payment commitment.[11][2]
Use a simple opening: “I need help with substance use, I do not have insurance, and I cannot afford the quoted price. Who handles financial assistance or referrals?” Have your location, the care recommended, and any insurance or benefits information ready. Ask what eligibility documents are required and whether you need an assessment before applying. Availability and requirements differ.
When the Rehab Quote Is Unaffordable
“I need treatment, but I cannot afford this amount. Who can help me check coverage, assistance, or another appropriate provider?” Ask for a named contact and the next application or appointment step.
If the first provider cannot help, request the name and contact details of a public or lower-cost service, then confirm that it accepts new patients and can meet your care needs. If a clinician recommended treatment, tell them where access broke down. You can ask for help arranging another option rather than restarting the search without support.[6]
Requesting a Good Faith Estimate
CMS explains that people who do not have insurance, or are not using it for care, can usually receive a written good faith estimate of expected charges. Providers generally must give one when care is scheduled at least three business days in advance or when requested. This process does not apply during emergency care.[4]
Tell the provider that you are uninsured or will not use insurance, and request the estimate in writing. CMS notes that current estimates generally cover one provider or facility, even when several are involved. Request an estimate from each relevant provider and the facility.[4]
What the Estimate Can and Cannot Tell You
A good faith estimate lists expected charges; it is not a bill or a guarantee that no additional care will be needed. Unanticipated services may not be included. Ask what assumptions the estimate uses and which services another provider may bill.[4]
Keep the written estimate and compare it with the eventual bill. CMS describes a dispute process when a provider’s bill is at least $400 above that provider’s estimate, with a deadline of 120 days after the initial bill. Review the official requirements for your situation before relying on that process.[4]
Comparing Payment Options
If a program offers a payment plan or financing, request the written terms. Compare the total amount, fees or interest, payment dates, and what happens if treatment changes or ends early. A monthly payment alone does not explain the full financial commitment.
You can use a simple comparison record for each option. Keep the clinical recommendation alongside the financial details so the cheapest quote is not mistaken for an equivalent service.
| Item to Record | Question to Resolve |
|---|---|
| Recommended care | Does this option provide the services the assessment identified? |
| Coverage | What has the insurer confirmed for this provider and service? |
| Expected personal cost | What deductible, copayments, coinsurance, or self-pay charges apply? |
| Separate bills | Which clinicians, medicines, tests, or other services are excluded from the quote? |
| Payment terms | What is the total commitment, including fees and cancellation terms? |
| Continuing care | What will the next phase require, and how will it be paid for? |
Keep an “unconfirmed” column in your notes for anything the program or insurer has not answered. For example, “facility covered; outside prescriber not yet checked” is more useful than writing “insurance covers rehab.” Follow up on those gaps before relying on a total estimate.[1]
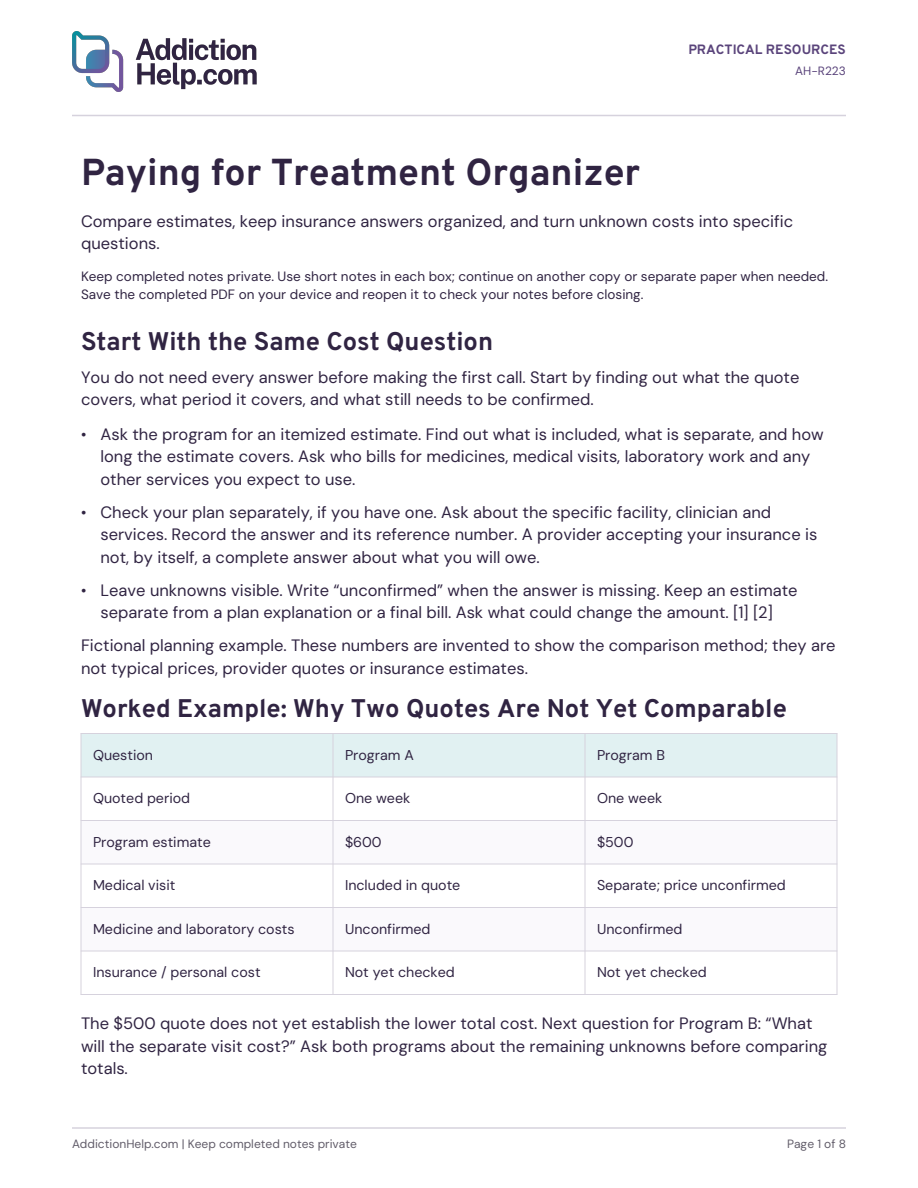
AddictionHelp.com · Practical resources
Paying for Treatment Organizer
Keep insurance answers, written estimates, payment questions, and follow-up notes together. Choose a shorter companion sheet when you need just one part of the task.
8-page fillable PDF · Free · No signup
Read Paying for Treatment Organizer online
For a related situation:
Plan for Medication and Continuing Care
Treatment may continue after a stay or structured program through medication, counseling, another service, or recovery support. Ask about the next phase before paying for the first. A quoted episode price does not establish the cost or arrangements for ongoing care.[6]
For opioid use disorder, medication treatment may continue after a stay or structured program. Confirm access to the prescribed medicine, follow-up visits, and coverage during the transition. Detox alone is not recommended as treatment for opioid use disorder.[12][13]
Budget for Care After Rehab
“After this program, where will follow-up and medication happen, and who checks that coverage?” Ask before discharge so the next phase does not begin with an unanswered payment question.
If coverage changes or a bill is disputed, tell the treatment team about any effect on access to care. Ask for help identifying alternatives and coordinating prescriptions or appointments. Do not independently stop a regularly used benzodiazepine because of a payment problem; abrupt discontinuation can be dangerous.[14]
If Coverage Is Denied or the Bill Looks Wrong
Request an explanation of what was denied or charged and compare it with the insurer’s documents and provider estimate. Ask whom to contact about a billing correction, coverage review, or appeal. SAMHSA’s insurance resource offers guidance on understanding coverage and getting help with problems.[1]
Keep copies of estimates, bills, relevant plan documents, and correspondence. If you were uninsured or self-paying and received a good faith estimate, check CMS’s dispute guidance promptly because time limits apply. That process has specific eligibility requirements; it is not a general promise that any disputed bill will be reduced.[4]
Find Help Paying for Rehab
Begin with the recommended care, then confirm coverage and request written cost details. If the first option is unaffordable, ask for help finding another suitable route. You can work on clinical and payment questions together rather than trying to solve the entire system before seeking support.
If you are in crisis or thinking about suicide, call or text 988 in the United States. Call 911 for an immediate life-threatening emergency.[11]
Compare rehab services and questions for choosing treatment, then use the treatment center directory to contact providers about availability and payment. If your assessment supports it, include outpatient care among the options. Keep the next step manageable: one provider, one coverage call, or one assistance application.
Frequently Asked Questions
Does Insurance Pay for All of Rehab?
Not necessarily. Covered services can still involve deductibles, copayments, coinsurance, network rules, and authorization requirements. Verify the specific program and service with your insurer and provider.[1]
Does a Gold Plan Pay Every Rehab Bill at 80 Percent?
No. Metal categories describe estimated cost sharing across covered care, not a fixed payment percentage for each individual bill. Actual costs vary by plan and the service involved.[3]
Can I Ask for Help Without Insurance?
Yes. Ask about public services, assistance, and lower-cost options, and use SAMHSA’s payment resources to explore routes to care. Availability and eligibility must be checked for the specific option.[2]
Is a Good Faith Estimate the Final Price?
No. It lists expected charges for the provider or facility and may not include unanticipated care or other providers’ bills. Keep it and compare it with the bill; CMS explains when a dispute process may apply.[4]
Get Treatment Help
If you or someone you love is struggling with addiction, getting help is just a phone call away, or consider trying therapy online with BetterHelp.
Exclusive offer: 20% Off BetterHelp*Following links to the BetterHelp website may earn us a commission that helps us manage and maintain AddictionHelp.com. *Get 20% off your first month of BetterHelp. Offer valid for new BetterHelp users only. Offer cannot be combined with insurance.
- Fact-Checked
- Editor